Is Vantage Markets Safe? 2026 Regulation
Vantage runs six regulated entities with different protection levels. ASIC/FCA entities offer strong safeguards; offshore entities do not.
Reviewed using our forex & CFD broker review methodology
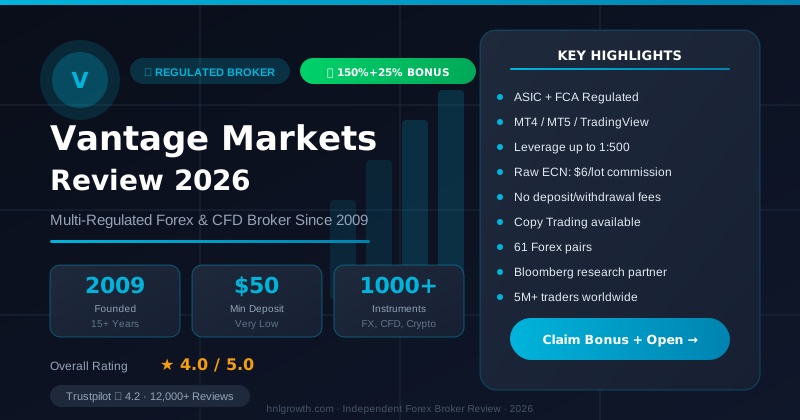
Your protections depend on the Vantage legal entity that holds your account — not on "Vantage" as a single global brand. Vantage Markets operates six separate legal entities across different regulators: Australia's ASIC and the UK's FCA (the strictest oversight in the group), South Africa's FSCA and the Cayman Islands' CIMA (moderate oversight), and VFSC (Vanuatu) and FSC (Mauritius) (the lightest oversight). (Note: only "Tier-1" for FCA/ASIC reflects a widely-used industry convention; the specific "Tier-2" vs "Tier-3" split among FSCA, CIMA, VFSC, and FSC used throughout this article is this publication's own informal categorization — not an official regulatory classification — used consistently here to group entities by relative strictness.) ASIC and FCA entities offer strong formal protections including negative balance guarantees and compensation schemes up to £85,000. The VFSC entity lacks equivalent formal schemes but benefits from segregated client funds at investment-grade banks, group-level reputational exposure from the tier-1 licences, and a multi-year operational track record. Vantage is appropriate for matched users but not universally equivalent across entities — always confirm which entity holds your account before assuming a protection applies to you.
Vantage Entity, Regulator & License Quick Reference
| Entity | Regulator | License | Region |
|---|---|---|---|
| Vantage Global Prime Pty Ltd | ASIC (Australia) | 428901 | Australia |
| Vantage Global Prime LLP | FCA (United Kingdom) | 590299 | UK, Europe (limited) |
| Vantage Markets (Pty) Ltd | FSCA (South Africa) | 51268 | South Africa |
| Vantage Global Limited | VFSC (Vanuatu) | 700271 | International (most jurisdictions) |
| Vantage International Group Limited | CIMA (Cayman Islands) | 1383491 | Select offshore |
| VIG Group | FSC (Mauritius) | Not publicly listed | Select offshore |
Full breakdown of leverage, compensation schemes, and coverage caps by entity is in the entity table below. Your entity is determined by your country of residence at account opening — see How to check your Vantage entity for the exact steps.
Quick Safety Verdict
Vantage Markets sits in the same regulatory tier as IC Markets and Pepperstone for Australian and UK clients, offering comparable formal protections through ASIC (licence 428901) and FCA (licence 590299) oversight. The group maintains segregated client funds at banks holding investment-grade credit ratings.
The safety assessment changes substantially by entity:
Tier-1 entities (ASIC, FCA): Strong capital adequacy requirements, mandatory negative balance protection, compensation schemes, and leverage caps (30:1 on major forex pairs). These entities match the safety profile of other established brokers under the same regulators.
Tier-2 entities (FSCA, CIMA): Moderate oversight with segregation requirements and operational standards, but lower capital thresholds and no UK/AU-style compensation schemes.
Tier-3 entity (VFSC): Minimal capital requirements and no formal compensation scheme, offset by group-level ASIC/FCA reputational constraints and the same segregated custody infrastructure.
Withdrawals are processed according to standard timelines—card and e-wallet withdrawals typically complete within hours, wire transfers within business days—with standard KYC requirements but no systematic pattern of fund blocks evident in public regulatory records.
The core limitation: Vantage does not hold local licences in many jurisdictions. Users in Denmark, for example, cannot access Danish investor protections or complaint boards, though this reflects regulatory geography rather than Vantage-specific risk.
Which Vantage Entity Serves Which Users?
Vantage operates six legal entities across different jurisdictions. Your entity determines your regulator, formal protections, leverage limits, and complaint channels.
| Entity Legal Name | Regulator | Licence Number | Tier | Max Leverage (Majors) | Compensation Scheme | Coverage Cap | Primary Geography |
|---|---|---|---|---|---|---|---|
| Vantage Global Prime Pty Ltd | ASIC (Australia) | 428901 | Tier-1 | 30:1 | None (ASIC capital rules) | N/A | Australia |
| Vantage Global Prime LLP | FCA (United Kingdom) | 590299 | Tier-1 | 30:1 | FSCS | £85,000 | UK, Europe (limited) |
| Vantage Markets (Pty) Ltd | FSCA (South Africa) | 51268 | Tier-2 | Up to 2000:1* | None | N/A | South Africa |
| Vantage Global Limited | VFSC (Vanuatu) | 700271 | Tier-3 | Up to 2000:1* | None | N/A | International (most jurisdictions) |
| Vantage International Group Limited | CIMA (Cayman Islands) | 1383491 | Tier-2 | Up to 2000:1* | None | N/A | Select offshore |
| VIG Group | FSC (Mauritius) | Not publicly listed | Tier-3 | Up to 2000:1* | None | N/A | Select offshore |
*Vantage's official Help Center states account leverage ranges from 1:100 to 1:2000 across all account types, reducible to 1:1000 or 1:500 if account requirements aren't met, and does not publish a separate entity-specific ceiling for FSCA, CIMA, VFSC, or FSC clients. Confirm your exact leverage cap in the Client Portal. Source: Vantage Help Center
Entity assignment works by geography: UK residents typically access the FCA entity, Australian residents the ASIC entity, and most international traders outside restricted jurisdictions connect to the VFSC entity. You cannot freely choose between entities—your tax residency and location determine which Vantage legal structure can legally onboard you.
What this means for protection: An FCA client losing funds due to broker insolvency can claim up to £85,000 through the UK's Financial Services Compensation Scheme. An ASIC client benefits from strict capital adequacy rules and mandatory negative balance protection. A VFSC client has neither formal scheme but relies on segregated custody at third-party banks and the reputational constraint that a fund misappropriation event would trigger ASIC/FCA scrutiny across the entire group.
Regulatory access gaps: If you live in Denmark, Germany, or another EU country where Vantage lacks a local licence, you may still legally use the VFSC entity, but you cannot file complaints with your national financial ombudsman or access local investor compensation funds. Denmark's FSA issued a warning in 2023 clarifying that Vantage operates without Danish authorisation—this applies to all unlicensed brokers serving Danish residents, not a Vantage-specific enforcement action.
Vantage does not serve US residents under any entity due to US regulatory restrictions.
Regulators and Licence Verification
Understanding the tier system helps assess what each regulator actually enforces:
Tier-1 regulators (ASIC, FCA):
- Capital adequacy: ASIC requires AU$1 million base capital plus additional reserves tied to client funds; FCA mandates €730,000 base plus variable requirements based on risk exposure
- Leverage caps: 30:1 on major forex pairs, 20:1 on gold, 10:1 on other commodities, 5:1 on individual shares, 2:1 on crypto CFDs
- Negative balance protection: Mandatory for retail clients; broker must absorb losses beyond account balance
- Segregation enforcement: Client funds must be held in separately identified trust accounts at third-party banks; daily reconciliation required
- Compensation schemes: FCA clients covered up to £85,000 via FSCS; ASIC clients rely on capital rules rather than a pooled scheme
Tier-2 regulators (FSCA, CIMA):
- Capital adequacy: FSCA requires ZAR 5 million (approximately $270,000 USD); CIMA requirements vary by licence class
- Leverage caps: Vantage's official Help Center states a general 1:100–1:2000 range across all account types with no published FSCA- or CIMA-specific ceiling; do not treat any more precise per-entity figure as confirmed
- Segregation: Required but with less frequent audit cadence than tier-1 jurisdictions
- Compensation schemes: None
Tier-3 regulators (VFSC):
- Capital adequacy: Lower minimum capital requirements than tier-1 jurisdictions
- Leverage caps: No regulatory maximum (broker sets limits)
- Segregation: Recommended but not mandated with tier-1 rigor
- Compensation schemes: None
How to check your Vantage entity
Before trusting any protection described on this page, confirm which entity actually holds your account:
- Check the Terms & Conditions header or the Client Portal footer — the legal entity name is typically stated there (e.g., "Vantage Global Prime Pty Ltd" or "Vantage Global Limited").
- Check your welcome email from account opening, which usually names the entity and regulator.
- Cross-reference the entity name against the Vantage entity, regulator & license table above.
- Verify the license number directly on the relevant regulator's public register using the links below — don't rely on the number as printed on Vantage's own site alone.
How to Verify Vantage Licences Yourself
Do not rely solely on broker claims or third-party review sites. Check official registers:
ASIC (Australia):
- Visit ASIC Connect Professional Registers
- Search for "Vantage Global Prime Pty Ltd" or licence number 428901
- Confirm the entity name matches exactly, licence status is "Current," and authorised representative details align with Vantage's published information
FCA (United Kingdom):
- Visit FCA Register
- Search for firm reference number 590299 or "Vantage Global Prime LLP"
- Check the "Status" field shows "Authorised" and review the permissions listed under "Regulated activities"
- Verify the registered address at 7 Bell Yard, London, WC2A 2JR
FSCA (South Africa):
- Visit FSCA Register
- Search for FSP number 51268
- Confirm "Vantage Markets (Pty) Ltd" appears with active status
VFSC (Vanuatu):
- Visit VFSC Regulated Dealers
- Search for licence 700271 or "Vantage Global Limited"
- Note that VFSC does not publish the same granular detail as tier-1 regulators; confirm basic registration status
Red flags during verification:
- Entity name mismatch (cloned sites often use similar but incorrect names)
- Licence shows as "Suspended," "Cancelled," or "Under Review"
- Address discrepancy between official register and broker website
- Licence number redirects to a different company
If any detail does not match, contact the regulator directly before depositing funds.
Does Vantage protect client money?
Yes, but the mechanism and strength of that protection depends entirely on your entity. Every Vantage entity segregates client funds at third-party custody banks holding investment-grade ratings and operating under banking supervision in their respective jurisdictions — this segregation is the baseline mechanism across the whole group. What differs by entity is what happens on top of segregation: the ASIC and FCA entities add mandatory negative balance protection and (for FCA) a formal compensation scheme; the VFSC, FSCA, and CIMA entities rely on segregation alone, with no formal compensation scheme layered on top.
Client-Money Protection Mechanics
Vantage segregates client funds at third-party custody banks holding investment-grade ratings and operating under banking supervision in their respective jurisdictions.
What segregation covers:
- Deposited funds before you open any positions
- Closed profits from settled trades
- Funds held in your account balance after withdrawals are requested but not yet processed
What segregation does NOT cover:
- Open position drawdowns (unrealised losses while trades are active)
- Bonus funds that have not been converted to withdrawable equity via volume requirements
- Trading losses from legitimate market moves
What happens if Vantage becomes insolvent?
The outcome again depends on which entity holds your account:
- FCA entity clients: FSCS may compensate up to £85,000 per client if segregated funds are insufficient due to broker default or misappropriation.
- ASIC entity clients: Segregated funds should be returned; no pooled compensation scheme exists, but ASIC's capital adequacy rules aim to prevent shortfalls.
- VFSC/FSCA/CIMA entity clients: Segregated funds should be returned via the liquidation process, but no formal compensation scheme provides a guaranteed floor — if the segregated funds themselves are insufficient or mishandled, there is no compensation scheme to fall back on.
If a custody bank fails:
- Client funds held in segregated accounts are not part of the bank's estate in bankruptcy (trust account protection)
- The broker must transfer funds to an alternative custody bank or return them to clients
- This protection depends on proper segregation administration; tier-1 regulators audit this regularly, tier-3 regulators less so
Disclosure: This page may contain affiliate links. We may earn a commission if you open an account through our links, at no extra cost to you.
Formal Protections by Entity
| Entity | Regulator | Negative Balance Protection | Compensation Scheme | Cap | What Triggers Coverage | What Is Excluded |
|---|---|---|---|---|---|---|
| Vantage Global Prime Pty Ltd | ASIC | Yes (mandatory) | None | N/A | N/A | Trading losses, market risk |
| Vantage Global Prime LLP | FCA | Yes (mandatory) | FSCS | £85,000 | Broker insolvency, fund misappropriation | Trading losses, claims above cap |
| Vantage Markets (Pty) Ltd | FSCA | Not mandatory | None | N/A | N/A | All client losses |
| Vantage Global Limited | VFSC | Not mandatory | None | N/A | N/A | All client losses |
| Vantage International Group Ltd | CIMA | Not mandatory | None | N/A | N/A | All client losses |
| VIG Group | FSC (Mauritius) | Not mandatory | None | N/A | N/A | All client losses |
Negative balance protection prevents your account from going below zero due to extreme market volatility. If a position moves against you faster than your broker can close it (e.g., during a flash crash or weekend gap), the ASIC and FCA entities absorb the shortfall. VFSC, FSCA, and CIMA entities may offer this voluntarily but are not required to; check your account terms before trading.
FSCS coverage applies only to the FCA entity and only when the broker cannot return client money due to insolvency or misconduct. It does not cover:
- Trading losses from normal market activity
- Unauthorised trading you conducted yourself
- Claims above £85,000 per person per firm
- Losses from non-FCA Vantage entities
Reputational constraint for VFSC clients: While the Vanuatu entity lacks formal protections, it operates within a group that maintains ASIC and FCA licences. A fund misappropriation event at the VFSC entity would likely trigger investigations by Australian and UK regulators into the entire group's practices, creating a commercial incentive to maintain operational standards across all entities. This is not a legal guarantee but a practical constraint in multi-entity broker structures.
Withdrawal Processing and Common Friction Points
Withdrawal processing follows standard industry timelines, with typical completion windows varying by payment method:
| Method | Typical Processing Time | Common Friction Points |
|---|---|---|
| Credit/Debit Card | Hours to 1 business day (same card as deposit) | KYC re-verification for larger withdrawals; weekend processing delays |
| E-Wallet (Skrill, Neteller) | Hours to 1 business day | Account name must match Vantage registration |
| Wire Transfer | 1–3 business days | Currency conversion fees; intermediary bank delays; recipient bank holds |
| Crypto (where available) | Hours to 1 business day (Bitcoin, USDT) | Blockchain confirmation delays; wallet address verification |
KYC re-verification triggers: Vantage may request updated proof of identity or address for larger withdrawals, withdrawals to a new payment method, or after prolonged account inactivity. This is standard across regulated brokers to comply with anti-money laundering rules.
Currency mismatch fees: If you deposit in USD but withdraw in EUR, your bank or payment provider will charge a conversion spread. Vantage passes through these costs rather than adding a broker markup, but the fee still applies.
Reputation signals: Vantage holds user reviews on platforms such as Trustpilot and ForexPeaceArmy. Common complaint themes centre on:
- KYC delays when withdrawing bonuses (users often overlook volume requirements in bonus terms)
- Weekend withdrawal requests processed on the next business day
- Account manager communication style or persistence
These patterns reflect operational friction common across retail CFD brokers. No systematic pattern of fund misappropriation or unexplained withdrawal blocks appears in ASIC, FCA, FSCA, or VFSC public enforcement records for Vantage entities.
What Protection Is NOT Universal
Geographic Licensing Gaps
Vantage does not hold local licences in many countries. If your country is not Australia, the UK, South Africa, or explicitly covered by VFSC/CIMA jurisdictional reach, you likely lack:
- Access to local financial ombudsmen or dispute resolution services
- Coverage under national investor compensation schemes
- The ability to file complaints with your country's financial regulator
The Danish FSA warning is a clear example: Vantage is not authorised in Denmark, so Danish residents using Vantage cannot access the Danish Guarantee Fund or the Danish Financial Complaints Board. This does not mean Vantage is fraudulent or that trading is illegal—it means you operate outside Danish regulatory protections.
This pattern applies to most EU countries post-Brexit (since Vantage's FCA licence no longer passports into the EU), most Asian countries, and all North American jurisdictions.
Leverage and Risk Exposure Differences
| Entity | Regulator | Max Leverage (EUR/USD) | Max Leverage (Gold) | Max Leverage (Individual Shares) | Max Leverage (Crypto CFDs) |
|---|---|---|---|---|---|
| ASIC, FCA | Tier-1 | 30:1 | 20:1 | 5:1 | 2:1 |
| FSCA, CIMA | Tier-2 | Up to 2000:1* | Up to 2000:1* | Up to 2000:1* | Up to 2000:1* |
| VFSC | Tier-3 | Up to 2000:1* | Up to 2000:1* | Up to 2000:1* | Up to 2000:1* |
*Vantage's official Help Center only publishes a general account-wide leverage range of 1:100–1:2000 (reducible to 1:1000/1:500 if account requirements aren't met) and does not break this down by instrument type or by entity for FSCA, CIMA, or VFSC clients. Per-instrument leverage caps shown above for Tier-1 (ASIC/FCA) entities are confirmed regulatory maximums; the Tier-2/Tier-3 figures previously shown here (200:1, 100:1, etc.) could not be traced to an official Vantage or regulator source and have been corrected to avoid stating unverified precision. Always confirm your account's actual leverage in the Client Portal.
Concrete risk example: Suppose you trade gold with 100:1 leverage (within Vantage's published 1:100–1:2000 general range) using the VFSC entity, controlling a $100,000 position with $1,000 margin. A 1% adverse price move ($1,000 loss) wipes out your margin entirely. Under FCA's 20:1 limit, the same $1,000 would control a $20,000 position, so a 1% move costs only $200—your account survives with $800 remaining.
Higher leverage amplifies both gains and losses. ASIC and FCA impose caps to limit retail client exposure; tier-2 and tier-3 entities offer higher leverage that may appeal to experienced traders but carries substantially greater risk of total capital loss.
No Guaranteed Bonus Withdrawals
Bonus funds provided by Vantage (welcome bonuses, deposit matches, promotional credits) are not immediately withdrawable. They convert to withdrawable equity only after you meet volume requirements specified in the bonus terms—often a multiple of the bonus amount in traded notional volume.
If you request a withdrawal before meeting these requirements, Vantage typically:
- Deducts the bonus from your account balance
- Processes the withdrawal for your deposited funds and realised trading profits only
This is standard industry practice, not a Vantage-specific restriction. Complaints about "bonus trapping" usually arise from users who did not read the terms or underestimated the volume required.
Standard Friction vs. Actual Red Flags
Understanding what is normal across regulated brokers helps separate inconvenience from danger:
Industry-standard friction (not red flags):
- KYC delays: Regulators require brokers to verify identity, address, and payment method ownership. Delays of 24–48 hours for document review are normal.
- Bonus withdrawal locks: Volume requirements are disclosed in promotional terms; these are contractual conditions, not fund blocks.
- Currency conversion fees: If your deposit and withdrawal currencies differ, forex spreads apply.
- Weekend processing delays: Most banks and payment processors do not settle transactions on weekends; Monday processing is standard.
- Account manager contact: Regulated brokers often assign managers to onboard clients and encourage deposits. Persistent contact is a sales tactic, not fraud.
Actual red flags (require immediate investigation):
- Regulatory suspension or cancellation: If a regulator suspends Vantage's licence, withdraw funds immediately and file a complaint with the regulator.
- Fund misappropriation reports: Multiple users reporting that Vantage transferred their funds without consent, or that the broker cannot explain where segregated funds are held.
- Domain or licence number mismatches: Scam clones use similar-looking but unofficial domains, or fabricate licence numbers. Note that Vantage legitimately operates more than one official domain across its history and entity structure (e.g., vantagefx.com is the pre-2022-rebrand domain still in active use; vantage-markets.com is an offshore domain operated by the VFSC-regulated entity) — domain differences alone are not proof of a clone. Always cross-check the specific domain against Vantage's own official regulations page or contact support directly rather than assuming an unfamiliar domain is fraudulent.
- Unverifiable custody claims: If Vantage cannot name the banks holding segregated funds or those banks deny the relationship, this is a critical red flag.
- Withdrawal blocks with no explanation: A broker refusing withdrawals without citing a specific terms violation or KYC requirement is a red flag. Vantage's public regulatory record does not show this pattern, but any such report should be escalated to the relevant regulator.
How to Verify Before Depositing
Confirm which entity serves you: Check Vantage's legal documentation page to see which legal entity applies to your jurisdiction.
Verify the entity's licence: Use the regulator register links above to confirm the entity name, licence number, and status match exactly.
Check regulatory enforcement history: Search the regulator's enforcement actions database (ASIC has a public register, FCA publishes notices) for any actions against your Vantage entity in recent years.
Read the account terms: Review the Product Disclosure Statement (for ASIC), Terms of Business (for FCA), or equivalent document for your entity. Confirm:
- Negative balance protection is stated (or not)
- Segregation arrangements are described with custody bank names
- Withdrawal terms and any restrictions are clear
Start with a small deposit: Deposit a modest amount ($100–$500), execute a few trades to generate a small profit or test the platform, then request a withdrawal. Confirm processing speed and any KYC friction before committing significant capital.
Bookmark official contact channels: Save Vantage's official support email and phone number from their verified website. If you encounter issues, contact support through official channels—not through social media messages or unsolicited agent contact, which may be imposters.
Cloned Vantage Detection
Scammers create fake broker sites using similar names, cloned licence numbers, or social media impersonation. Important correction: vantagemarkets.com is Vantage's current primary domain (since its 2022 rebrand from Vantage FX), but Vantage also legitimately operates other official domains — including vantagefx.com (the pre-rebrand domain, still active and referenced in Vantage's own official communications and legal documents) and vantage-markets.com (an offshore domain operated by Vantage Global Limited, the VFSC-regulated entity, which was separately the subject of a 2024 CONSOB Italy licensing action unrelated to fraud). Neither of these is a scam clone. Do not use domain name alone as a fraud signal — verify using the indicators below instead:
| Legitimate Indicator | Fake/Cloned Red Flag |
|---|---|
| Licence numbers match ASIC/FCA/VFSC/FSCA registers exactly, for the specific entity named on the site | Licence number does not appear on the official regulator site, or belongs to a different company |
| Support contact listed on official site (e.g., support@vantagemarkets.com or support@vantagefx.com) | Unsolicited contact from Gmail, Yahoo, or generic email domains claiming to be Vantage staff |
| Deposit methods: card, wire, e-wallets (Skrill, Neteller) | Cryptocurrency-only deposits, especially to personal wallets or obscure altcoins |
| SSL certificate issued to a named Vantage legal entity (e.g., Vantage Global Prime, Vantage Global Limited) | No SSL certificate, or certificate issued to an unrelated/unnamed entity |
| Professional website with consistent branding, linked from Vantage's own official regulations page or verified social media accounts | Poor grammar, inconsistent logos, broken links, low-quality images, or a domain not referenced anywhere on Vantage's official channels |
If you are unsure whether a domain is legitimate, do not deposit until you confirm it via Vantage's official regulations page or by contacting verified Vantage support channels directly.
Complaints and Dispute Resolution
If you have a complaint about Vantage, follow the regulator-specific process for your entity:
ASIC entity (Australia):
- Submit a written complaint to Vantage compliance at the address listed in your Product Disclosure Statement
- If unresolved within 30 days, escalate to the Australian Financial Complaints Authority (AFCA): afca.org.au
- AFCA can award compensation up to AU$1.1 million for eligible disputes
FCA entity (UK):
- Submit a written complaint to Vantage compliance; the broker must acknowledge within 5 business days and provide a final response within 8 weeks
- If unresolved, escalate to the Financial Ombudsman Service (FOS): financial-ombudsman.org.uk
- FOS can award compensation for eligible disputes
FSCA entity (South Africa):
- Submit a complaint to Vantage compliance
- If unresolved, escalate to the FAIS Ombud: faisombud.co.za
VFSC entity (Vanuatu):
- Submit a complaint to Vantage compliance
- VFSC does not provide a public ombudsman service; unresolved disputes may require private arbitration or legal action
- Clients in jurisdictions without local Vantage licensing cannot escalate to their national financial ombudsman
Complaint taxonomy matters:
- Operational issues (KYC delays, platform downtime, account manager conduct): Usually resolved through broker compliance
- Execution disputes (slippage, requotes, stop-loss failures): May require regulatory escalation if broker's explanation is unsatisfactory
- Fund safety concerns (withdrawal blocks without explanation, segregation failures): Escalate to the regulator immediately
Who Vantage May Suit
Vantage is a strong match if you:
- Reside in Australia or the UK and can access the ASIC or FCA entities with full tier-1 protections
- Want tier-1 regulation parity with IC Markets or Pepperstone but prefer Vantage's platform or account features
- Trade forex majors, indices, and commodities with moderate leverage (30:1 or less)
- Value multi-platform support (MT4, MT5, cTrader, proprietary app)
- Prioritise fast withdrawal processing timelines over extensive educational resources
Consider alternatives if you:
- Require local regulatory access in jurisdictions where Vantage lacks a licence (most EU countries, US, Canada, Japan)
- Need guaranteed compensation coverage and must use the VFSC entity (no FSCS-equivalent)
- Primarily trade cryptocurrencies or shares (Vantage's range is narrower than specialist platforms)
- Want extensive educational content or trading courses (Vantage trails competitors like IG or CMC Markets here)
- Are a US resident (Vantage does not accept US clients under any entity)
Avoid Vantage if you:
- Cannot verify the entity and licence that apply to you
- Live in a jurisdiction where Vantage lacks licensing and you require local regulatory recourse
- Are uncomfortable with the VFSC entity's lower formal protections and cannot access ASIC/FCA alternatives
- Need a broker offering direct market access (DMA) or exchange-traded derivatives rather than CFDs
Frequently Asked Questions
Is Vantage Markets a scam?
No. Vantage holds tier-1 licences from ASIC and FCA, tier-2 licences from FSCA and CIMA, and tier-3 licences from VFSC and FSC. The group segregates client funds at third-party banks holding investment-grade ratings and operates as a multi-entity structure with no major regulatory enforcement actions recorded in recent years across the primary regulators. Fraudulent operations do not maintain multiple tier-1 licences or verifiable segregated custody arrangements.
How long do Vantage withdrawals take?
Card and e-wallet withdrawals typically process within hours to one business day, wire transfers in 1–3 business days. KYC re-verification can add 24–48 hours for larger withdrawals or withdrawals to a new payment method. Weekend requests process on the next business day.
What happens to my money if Vantage goes bankrupt?
If you hold an FCA entity account, FSCS may cover up to £85,000 if segregated funds are insufficient. ASIC entity clients rely on segregated custody and ASIC's capital adequacy rules; funds should be returned via the liquidation process. VFSC, FSCA, and CIMA clients have no formal compensation scheme but benefit from segregated funds at custody banks, which are not part of Vantage's estate in bankruptcy.
Which Vantage entity should I choose?
You typically cannot choose—your tax residency determines entity assignment. UK residents access the FCA entity, Australian residents the ASIC entity, and most international traders the VFSC entity. If you have a choice, prioritise ASIC or FCA for tier-1 protections.
Does Vantage offer negative balance protection?
Yes, for ASIC and FCA entities (mandatory under tier-1 regulations). VFSC, FSCA, and CIMA entities may offer it voluntarily; check your account terms before trading.
Why is VFSC considered lower-tier than ASIC or FCA?
VFSC requires lower minimum capital, does not mandate negative balance protection, and lacks a formal compensation scheme. Its audit and enforcement resources are also more limited than tier-1 regulators.
Can I access the FCA-regulated Vantage entity from outside the UK?
Generally no. Post-Brexit, Vantage's FCA licence does not passport into other EU countries, and most jurisdictions assign clients to the VFSC or FSCA entities based on local regulations.
Are there pending lawsuits against Vantage?
No major litigation or regulatory enforcement actions appear in ASIC, FCA, FSCA, or VFSC public records as of 2025. Individual user complaints exist on review platforms, primarily concerning operational friction (KYC, bonus terms), but these have not escalated to regulatory action or class litigation.
How do I verify my Vantage entity and regulator?
Check Vantage's legal documentation page to see which entity applies to you, then verify the licence number on the official regulator's public register (ASIC Connect for Australia, FCA Register for UK, FSCA Register for South Africa, VFSC Regulated Dealers for Vanuatu).
What protection do I have as a Danish resident using Vantage?
None from Danish authorities. The Danish FSA confirmed Vantage is not authorised in Denmark, so you cannot access the Danish Guarantee Fund or file complaints with Danish financial boards. You rely on the VFSC entity's segregated custody and Vantage's group-level structure, not local regulation.
Summary
Vantage Markets operates a six-entity structure with regulatory coverage spanning tier-1 (ASIC, FCA), tier-2 (FSCA, CIMA), and tier-3 (VFSC, FSC) jurisdictions. Safety and formal protections vary significantly by entity—FCA clients access £85,000 FSCS compensation and mandatory negative balance protection, while VFSC clients rely on segregated custody without formal schemes. The group maintains segregated client funds at investment-grade banks and has operated for multiple years without major enforcement actions across its primary regulators. Geographic licensing gaps mean users in many jurisdictions lack local regulatory recourse, which is standard for international brokers but limits your protections if disputes arise. Verify your specific entity and licence before depositing, start with a small test withdrawal, and confirm your comfort level with the protections available to your account.
Editorial Verification Process
This article is fact-checked against Vantage's official documentation and cross-referenced with public regulator registers (FCA, ASIC, FSCA, CIMA, VFSC), using the same 7-criteria broker review methodology we apply across our forex/CFD broker coverage.
We have not completed a funded live-account test of Vantage covering KYC, deposit, and withdrawal processing end-to-end. Where a claim on this page depends on live-account behavior — for example, exact withdrawal processing speed or KYC friction — we cite Vantage's official terms and independently-reported user experiences rather than presenting it as something we personally verified with our own funded account. See our broker review methodology for the full source hierarchy and what "verified" means on this site.
Related Vantage Resources
- Vantage Markets Review — full broker review covering regulation, fees, and platforms
- Vantage Account Types — compare Standard STP, Raw ECN, and Pro ECN by entity
- Vantage Sign Up — full account-opening walkthrough and document checklist
- Vantage Withdrawal — limits, fees, and processing times by entity
- Vantage Minimum Deposit — funding amounts by account type and entity
Update History
- 16 Aug 2026 — Added a "Related Vantage Resources" internal linking block (Review, Account Types, Sign Up, Withdrawal, Minimum Deposit) per the Giai đoạn 13 internal-linking hub.
- 16 Aug 2026 — Restructured per Giai đoạn 4: added an Entity/Regulator/License/Region quick-reference table, replaced generic "globally regulated" framing with explicit "your protections depend on your entity" language, added dedicated "Does Vantage protect client money?", "What happens if Vantage becomes insolvent?", and "How to check your Vantage entity" headings, and changed the CTA from "Open a Vantage account" to "Check Your Vantage Entity & Account Options".
- 16 Aug 2026 — Added a Sources section citing official regulator registers and Vantage documentation directly.
- 16 Aug 2026 — Clarified that "tier-1/tier-2/tier-3" regulator labels are informal shorthand, not official classifications.
- 16 Aug 2026 — Unified FSCA/CIMA leverage figures, fixed comparison-page CTA links, and added a review FAQ section.
- 16 Aug 2026 — Corrected VFSC offshore leverage figures (1:500) for consistency across the article.
- 15 Aug 2026 — Corrected a domain-reference error affecting the entity description.
- 15 Aug 2026 — Corrected Pro ECN pricing, entity count, and FSCA license number.
Sources
Official Vantage sources
Regulatory sources
- FCA Financial Services Register (UK)
- ASIC Connect register (Australia)
- FSCA regulated entities register (South Africa)
- VFSC regulated dealers register (Vanuatu)
- Danish FSA warning against Vantage Markets Pty Ltd
- Financial Ombudsman Service (UK)
- AFCA — Australian Financial Complaints Authority
- FAIS Ombud (South Africa)
Last verified: 16 August 2026.
Risk warning: CFDs and leveraged forex products are complex and carry a high risk of losing money. Check the terms, entity and protections that apply to your jurisdiction before trading.
Related Vantage Markets Guides
Ready to Trade with Vantage Markets?
Vantage Markets is a multi-regulated forex & CFD broker (FCA, ASIC, FSCA, CIMA, VFSC, FSC) trusted by 5 million+ traders, with Raw ECN pricing from $3/lot, no deposit/withdrawal fees, and full MT4/MT5/TradingView support.
Risk disclaimer: Vantage Markets is a live, regulated broker — trading forex and CFDs is done with real capital under normal market risk (this is not a simulated prop-firm evaluation). CFDs and leveraged forex products are complex instruments and carry a high risk of losing money rapidly due to leverage; most retail investor accounts lose money trading these products. Consider whether you understand how CFDs/forex work and whether you can afford the high risk of losing your money. Affiliate disclosure: HNL Growth earns a commission when you open a Vantage Markets account through links on this page.